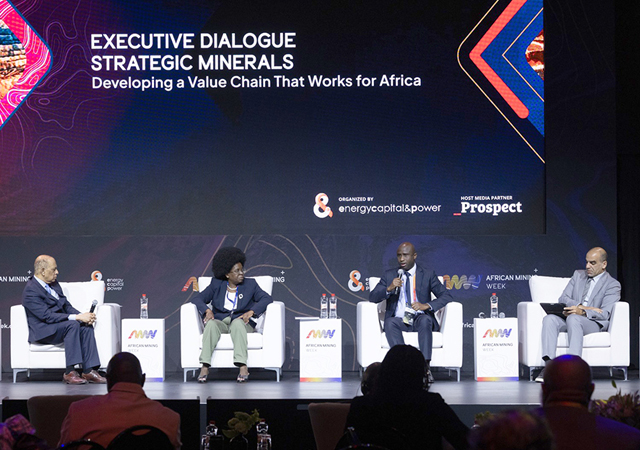
 An ongoing session at African Mining Week 2026
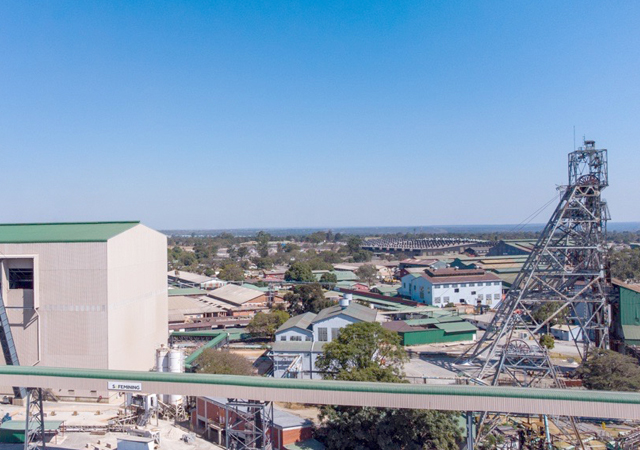
As global demand for metals continues to rise, a growing number of African countries are seeking to move beyond their traditional role as suppliers of raw minerals and establish themselves as producers of higher-value metal products.
The trend was on full display at African Mining Week (AMW) 2026 in Cape Town, where government officials outlined ambitious plans to expand refining, smelting and processing capacity across the continent’s metals value chain.
Leading the charge is Guinea, the world’s largest exporter of bauxite, which is pursuing an aggressive industrialisation strategy aimed at transforming its vast mineral wealth into a foundation for domestic manufacturing.
The country plans to have five alumina refineries operating by 2030, with three already under construction. The initiative forms a cornerstone of the government’s Simandou 2040 strategy, a long-term development framework designed to shift Guinea from a raw-material exporter to a regional industrial hub.
Speaking during a ministerial panel at the event, Daouda Diakité, Senior Adviser to Guinea’s Minister of Mines and Geology, said the country is targeting between seven and eight million tonnes of annual alumina production capacity by the end of the decade.
The strategy reflects a broader effort to build an integrated metals industry around Guinea’s extensive bauxite and iron ore reserves. Alongside alumina refining, authorities are advancing plans for domestic steel production linked to Simandou iron ore project, one of the world’s largest undeveloped iron ore deposits.
“Simandou 2040 is a strategy to shift from being a raw material exporter to developing a strong processing base that can sustain the country’s downstream sector. To achieve this, we are encouraging investment in domestic aluminum and steel production, as well as power projects that can support downstream development,” Diakité said.
The emphasis on steel production is particularly significant. Historically, much of Africa’s iron ore has been exported for processing elsewhere, limiting the economic benefits retained within producing countries. Guinea’s plans suggest a determination to change that equation by creating domestic capacity that can support manufacturing, infrastructure development and job creation.
“The steel from Simandou has to be processed in Guinea, and we are finishing the feasibility study for that,” Diakité added. Guinea is also progressing plans for a domestic gold refinery, further broadening its downstream metals portfolio and signaling a wider commitment to value-added mineral processing.
Elsewhere, Uganda is positioning itself as a regional refining hub, leveraging existing infrastructure to provide processing services for neighboring countries. The country currently operates 10 gold refineries and is actively promoting toll-processing arrangements.
According to Monica Musenero Masanza, Uganda’s Minister of Energy and Mineral Development, the model offers both economic and sustainability advantages, with refining operations powered by surplus renewable energy.
“Rather than every nation enduring the high cost of building refineries, Uganda offers a regional solution. We allow our East African neighbors to bring gold in tax-free for toll processing, and because our operations run on excess renewable energy, the final product is truly green gold,” she said.
Uganda’s ambitions extend beyond precious metals. The country is investing in high-purity tin production while expanding beneficiation of iron ore and phosphate resources to support domestic steel manufacturing and fertilizer production.
“Uganda’s rapid development requires massive amounts of steel and fertilizer. With 14 companies lined up to produce steel billets from local iron ore and active plans to process our phosphate reserves, we are adding value to our minerals directly to build our infrastructure and fuel our agricultural needs,” Masanza said.
Supporting these industrial ambitions is a growing recognition that metals processing requires robust logistics and energy infrastructure. Egypt is seeking to capitalize on this opportunity by positioning itself as a strategic partner for mineral-producing nations across Africa.
Mohamed Zada, Egypt’s Deputy Minister for Strategic Industries, highlighted the role of ports, power generation and transport corridors in strengthening Africa’s metals supply chains and improving the competitiveness of locally processed products in international markets.
“Egypt’s strategic location makes it a natural logistics hub. By partnering across the continent to build power plants and seaport infrastructure, we can optimise supply chains and bring Africa’s finished mineral products to global markets,” he said.
Taken together, the announcements at AMW 2026 point to a notable shift in Africa’s metals sector. Rather than focusing solely on mineral extraction, governments are increasingly pursuing integrated value chains that encompass refining, smelting, manufacturing and export logistics.
For investors, the opportunity is no longer confined to mining projects alone. Refining facilities, steel plants, power generation assets and transport infrastructure are emerging as critical components of the continent’s industrial future, as African nations seek to ensure a larger share of the value generated from their metal resources remains at home.