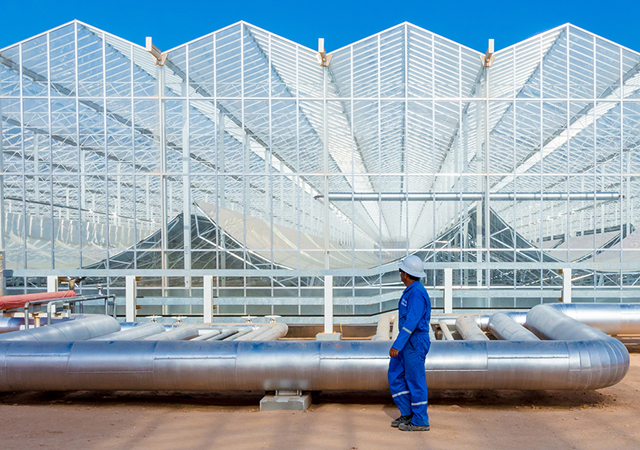
 Miraah, GlassPoint’s large-scale solar steam project in Oman, uses enclosed trough technology to generate steam for enhanced oil recovery (Solar EOR).
Securing the fuels, power and heat needed to keep the Gulf’s vibrant economies running is an essential piece of energy security. We have seen this first hand recently with the UAE’s decision to leave the Organization of the Petroleum Exporting Countries (Opec) and Opec+ to continue investment in domestic and renewable energy capacity, while more broadly countries across the Gulf are looking for greater control over how their economies are powered.
Industrial heat is a lesser discussed, but hugely important part of this energy security challenge.
From oil and gas to metals and mining, industry need to generate massive amounts of process heat, and today, that’s largely done by burning natural gas or other fossil fuels. That means the availability and price of these resources directly affects the cost of running a plant, leaving industry exposed when traditional energy markets are disrupted.
What we have seen since February in the Strait of Hormuz has triggered significant supply and cost volatility for heavy industry in the region and beyond. To put it into context, roughly a fifth of the world’s oil and almost all of Qatar’s and the UAE’s liquefied natural gas (LNG) passes through the Strait, and the fallout, according to Brussels-based think tank, Bruegel, pushed oil prices up by about 8 per cent, and European gas by roughly 20 per cent. Months later, the disruption is still being felt. The IEA reported that Gulf oil exports fell by 2.1 million barrels a day in July after the passageway was effectively closed again, with loadings dropping from around 20 million barrels a day at the start of the month to about 12 million later in July.
Rod MacGregor.
This chokepoint has created a plethora of widely reported issues across the world, but from an industrial heat perspective, it has exposed the trilemma that has always existed: how to secure process heat that simultaneously provides stable low prices, reliability and fewer emissions.
But for those in the sunniest parts of the world, there may now be a better answer. And it’s never mattered more.
The trilemma, defined
Industrial heat accounts for a massive 20 per cent of global energy demand, and is among the largest sources of industrial emissions, releasing roughly 10Gt of CO2 annually. It is one of the hardest source of emissions to abate because the heat is derived overwhelmingly from combustion that cannot be cleaned up downstream.
For decades, economics forced industry to settle for one or, at a push, two of the three priorities: cheaper energy, reliable supply or lower emissions. The World Energy Council tracks this annually in its World Energy Trilemma Index.
In the Gulf, gas has historically been cheap and dependable because it is abundant, runs on existing infrastructure, and burns on demand, but combustion keeps emissions high. However, as the Hormuz disruption has shown, even its affordability rests on prices that can swing overnight. The electricity route, if sourced from renewables, is cleaner as it cuts emissions, but runs on power that costs several times more than gas per unit of energy, and reliability varies with sun, wind and grid capacity.
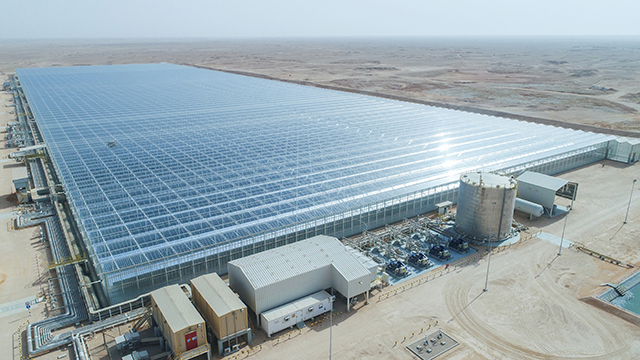
Solar EOR: operators are looking to reduce their exposure to fuel market volatility.
Industry’s choices were either to select the fuel that solves for cost and security (though even this is now being brought into question) but creates emissions, or the renewable electric routes that lower emissions, but raise costs, weaken reliability and often struggle to deliver at gigawatt scale.
Today, national strategies and leading operators across the GCC expect cost, security and lower emissions without compromise. ‘Pick two’ no longer satisfies either industry or government.
The Gulf’s advantage
This is where the Gulf has an edge. Hydrocarbons have long been the region’s strength in terms of energy, but it also has the added advantage of sunlight and open land in abundance.
Solar power is flourishing as a result. Dubai’s Mohammed bin Rashid Al Maktoum Solar Park, for example, reached 3,860 megawatt (MW) of capacity at the start of this year, after adding 1,000 MW during 2025, and is now expected to exceed 8,000 MW by 2030. But, while concentrated solar power (CSP) for electricity is well established, concentrated solar thermal (CST) for heat remains relatively untapped.
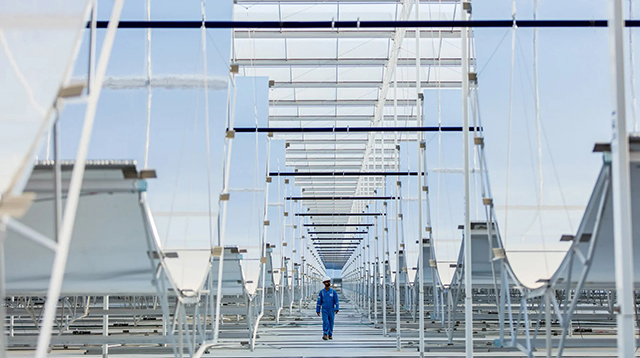
If the master key to industrial heat has been sunlight, no region is better placed to leverage it than the GCC.
CST captures sunlight to generate steam directly, without having to first turn it into electricity, and it produces five to six times more thermal energy per unit of land compared to utility-scale photovoltaics.
Our project economics show that, applied to industrial heat, direct solar steam can be delivered at around $44/MWh (megawatt-hour) on fixed 20-year terms, with no fuel bill attached. Affordable, secure and low-carbon all at once, and deliverable at the scale heavy industry demands.
For the Gulf, that goes straight to the heart of energy security. Every tonne of steam produced from gas keeps the industry tied to the price and availability of that fuel. Solar thermal gives operators another source to draw on, reducing that dependence with something the region has in abundance, and no market shock can reprice – sunlight.
No electricity, no gridlock
Electrification has been the default alternative for cleaner industrial heat, with electric boilers, green hydrogen and thermal batteries all relying on electricity as the intermediary.
However, electricity has an expensive ‘middleman’. Grid electricity has historically cost three to five times more than gas per unit of energy, and taxes and network charges alone can account for up to half its price.
So even when solar-powered electricity is at record-low prices, converting sunlight into power only to turn it back into heat creates superfluous steps that a sun-rich country does not need. The price plunge is compelling too. An electric boiler using grid electricity would cost roughly $135/MWh, whereas CST can deliver for $44/MWh.
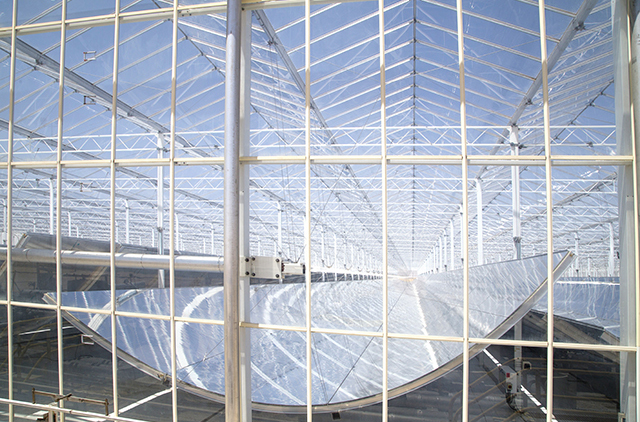
Industrial heat is an important part of the GCC’s energy security strategy.
Direct solar steam, paired with molten salt storage that carries heat through the night, offers continuous supply at a scale that electric alternatives have not approached.
There is evidence to support this. A recent peer-reviewed study found that in regions with strong solar resources, CST can cut energy costs and carbon emissions at the same time, overturning the assumption that cleaner heat must always cost more. At a gas price of around $50/MWh, the report found that solar thermal could economically supply more than 50 per cent of industrial heat demand in parts of the world below 45 degrees latitude. This number rises to about 90 per cent in Saudi Arabia because of the strength of its sunlight. In several countries modelled across the Gulf in fact, replacing gas with solar heat produced a negative cost of carbon abatement, saving between $120 and 180 per tonne.
Proof at scale
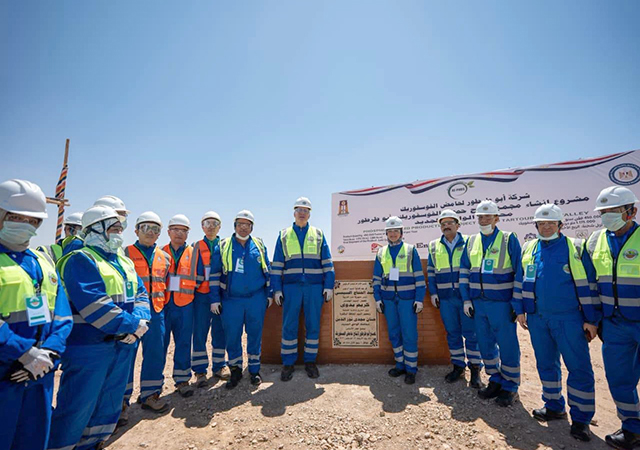
The Gulf is already deploying CST at scale. In Saudi Arabia for example, Ma’aden Solar 1 at Ras Al Khair is being built to deliver 500 MWth of thermal output continuously, from 1.5 GWth solar array, making it the largest solar process heat project in the world. Comparable electrified heat projects typically deliver around 7 MW, with the largest deployed peer project at roughly 50 MW.
It is also proven to be dependable infrastructure. The 330 MWth Miraah plant we worked on in neighbouring Oman, has been delivering 2,000 tonnes of steam a day since 2017, even through sandstorms and extreme weather events.
The payoff
Across the Gulf, industrial growth is written into national economic plans. Saudi Arabia’s National Industrial Strategy is targeting manufacturing GDP of SR895 billion by 2030, while the UAE’s Operation 300bn aims to more than double industry’s contribution to GDP to AED300 billion by 2031. Oman’s Industrial Strategy 2040 is built around developing a more advanced, competitive manufacturing base, while Bahrain’s industrial strategy similarly targets a larger contribution from industry, higher exports and stronger regional supply chains.
That growth will need heat to power the processes behind it. The question is whether every new factory and every extra tonne of output should mean another call on gas or other fossil fuels. From an energy security perspective, reducing the amount of gas needed for steam gives the region more room to maneuver as operators are less exposed to fuel price volatility and supply disruption, while gas can be preserved for other high value uses such as power generation, desalination, industrial feedstock or export.
For decades, industry treated the trilemma as a fact of life. Industrial heat could not be affordable, reliable and low-carbon simultaneously. Operators had to choose the one or two features that were most important at the expense of the third. However, the trade-off hinges on the fuel that is being used. Across the Gulf, that ‘fuel’ is abundant, free at source, and immune to disruption - sunlight. If the master key to industrial heat has been sunlight and land all along, no region is better placed to leverage it than the GCC.